How Nigerian Agritech Startup Zowasel Is Changing The Lives Of Smallholder Farmers

By Nao Fuwa  |  November 29, 2022

In Africa, many agritech startups are developing businesses to solve the problems smallholder farmers face. These challenges are numerous and significant, including crop damage from natural disasters, high food wastage due to supply chain inefficiencies, and limited access to financial services. According to a report by the United Nations, Nigeria has the highest “per capita food waste rate” in Africa, estimated at 40% to 50%.


Many agritech startups begin their business from a single point in the agricultural supply chain. For example, they set up marketplaces that connect farmers (sellers) and companies (buyers). In the past few years, many startups that began as marketplaces pivoted their business to agricultural supply chains, such as cold storage and cold storage vehicles to prevent waste of farm products, or companies that manufacture processed farm products.


Zowasel, a Nigerian agritech startup, is one such company that comprehensively addresses the issues faced by smallholder farmers.

[Jerry (right), CEO of Zowasel, a cocoa farm in Ondo State, Nigeria]

Jerry Oche was born into a farming family in northeastern Nigeria, and before founding Zowasel, he ran a crowdfunding business for small farmers. The crowdfunding business model was to sell the harvested crops and return the profits to investors, but it did not work out. The main reason was that small-scale farmers did not have appropriate sales outlets and could not sell their products at appropriate prices.

To solve this problem, Jerry founded Zowasel in 2017 as a marketplace business where farmers (sellers) and companies (buyers) could trade at an appropriate price. Over the years, the company started providing production guidance to farmers, selling inputs such as fertilizers and agrochemicals at lower prices than market prices, supporting opening bank accounts, etc.

Currently, in cooperation with Mitsubishi Corporation (MC) Nigeria, the company is implementing a farm machinery rental business for smallholder farmers and conducting a demonstration experiment of a credit-scoring business in cooperation with the Japan International Cooperation Agency (JICA).

A One-Stop Solution to the Challenges Facing Small Farmers

In order to provide an end-to-end solution to smallholder farmers, Zowasel has its main business is spread across 5 key verticals

(1) Marketplace (increase in profits and reduction of food loss)

(2) Crop cultivation education (improvement of cultivation knowledge) 

(3) Introduction of farm machinery (production efficiency improvement)

(4) Credit scoring (improving access to finance) 

(5) Traceability (visualization of distribution channels)

Currently, the company has a network of over 2 million smallholder farmers and about 5,000 sales partners. The agritech’s activities have expanded to many states in Nigeria. Its sales partners include major companies such as Olam, an agricultural general trading company headquartered in Singapore, Promasidor, based in South Africa, and Ireland’s Guinness.

In addition to providing fertilizers, seeds and guidance on appropriate cultivation & harvesting methods, the introduction of agricultural machinery by the startup has greatly improved productivity. Furthermore, Zowasel has removed the middlemen (usually 2 to 5 companies) from the supply chain, creating a win-win situation for farmers.

Now the farmers can sell at better prices, and companies can purchase farm products at lower prices. As a result, small farmers who have business relationships with Zowasel have seen their profits increase by an average of 30%.

Marketplace


Zowasel provides an online trading platform that connects small-scale farmers with companies and enables them to buy and sell at appropriate prices.

There are three major challenges faced by small-scale farmers when buying and selling agricultural products: (1) lack of understanding of appropriate market prices, (2) lack of sales channels, and (3) logistics for transporting agricultural products.

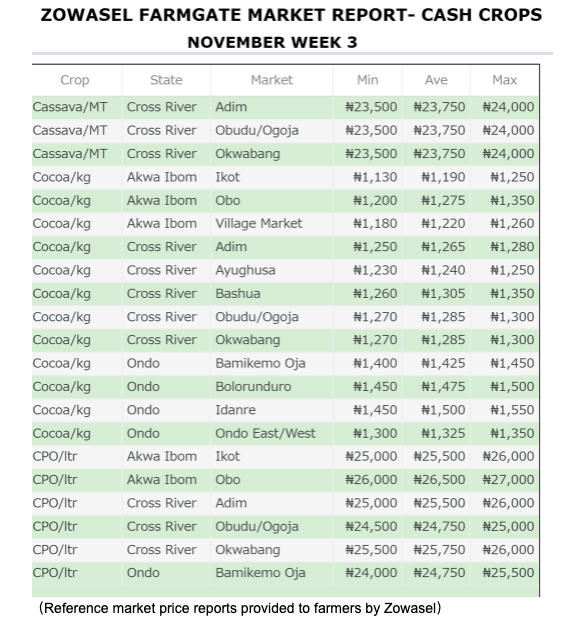
Zowasel researches and provides farmers with weekly reports of market prices for each agricultural commodity by region. The price list (below) shows the market prices of cassava and cocoa by region as surveyed by Zowasel.
When selling their produce, farmers determine the selling by themselves or with assistance from Zowasel, if needed. Every product undergoes quality inspections by Zowasel and is then entered into the online platform. By matching these data with the requirement entered online by the company (buyer), the transaction is concluded at a price that benefits both parties while eliminating the middleman. The final transaction price is determined through negotiations between the seller and buyer.

Another feature of the system is the use of mobile money to streamline payment. It is inefficient for both parties to travel great distances to make cash payments for sales. Since many smallholder farmers do not have bank accounts, Zowasel also assists them in opening bank accounts.

The company also provides logistics services after the transaction is completed, allowing customers to safely transport fresh products by hiring a carrier in partnership with Zowasel.

In addition, Zowasel has set up offices in each region to provide support to farmers who do not own cellphones & thereby, cannot use online trading and payment systems.
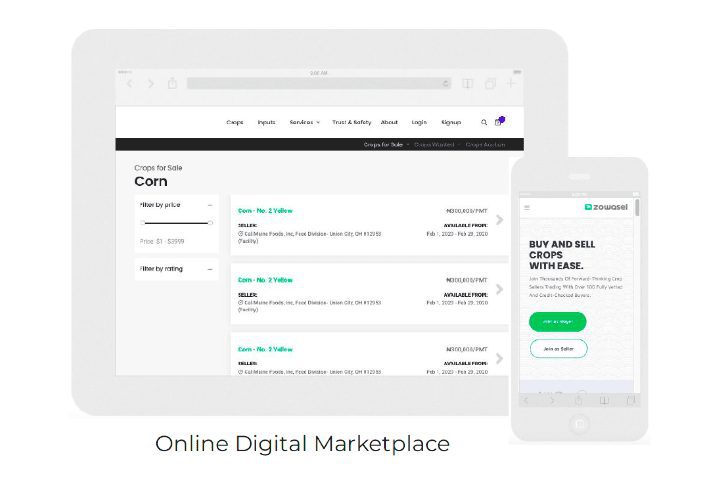
(Online platform provided by Zowasel)

Education on crop cultivation

Lack of uniformity in crop production and inconsistent quality & quantity are other challenges faced by smallholder farmers. In most cases, the problem is due to ‘inexperience’ in cultivation techniques.

Zowasel provides free education to smallholder farmers on the cultivation of each crop, storage after harvest, and cutting fertilizer costs. It also updates current crop sales market trends and helps farmers grow their farming businesses.

The company offers 24-hour customer support, where farmers can call and talk to experts about commodity market trends and ways to improve their businesses.
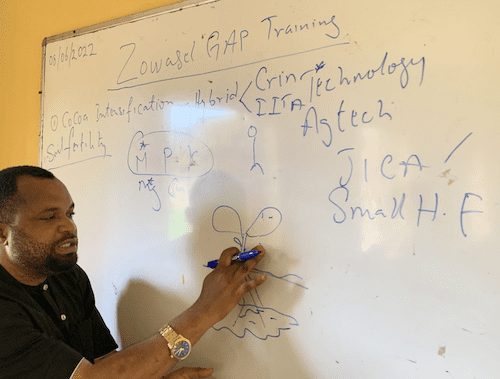
(One of the classes offered by Zowasel)

Agricultural machinery rental business

Many smallholder farmers in Nigeria have difficulty purchasing agricultural machinery owing to their low incomes, and much of their farming is still done manually. As a result, the yield of harvest remains low.

On the other hand, the number of farmers leaving farming in Japan is increasing due to the ageing of the farming population. Many farmers are transferring or scrapping their farm machinery, and many unused, used farm machines are available in Japan. In addition, pre-owned machinery in Japan used for the cultivation of small fields meets the needs of smallholder farmers in Nigeria.

Therefore, in order to improve agricultural productivity through the diffusion of agricultural machinery to smallholder farmers in Nigeria, Zowasel and MC Nigeria have started a demonstration experiment of an agricultural machinery rental business in Nasarawa State. A total of four machines, an Iseki tractor, a Kubota combine harvester, and two hand-pushed rice transplanters manufactured by Kubota and Yanmar, were imported from Japan to provide rental services to farmers. This rental business, which started this year, is going well. Rental demand for agricultural machinery is strong, and the reservation list is full of requests from farmers.

Mr Makoto Saito, CEO of MC Nigeria, said, “Through the demonstration test, we are measuring the impact of agricultural machinery on farmers’ productivity and income and analyzing the economic rationale for the agricultural machinery rental business. If we can introduce a business-oriented agricultural machinery service, the Nigerian agricultural market will change dramatically. The potential is enormous.”

However, there are issues to be addressed in the farm machinery dissemination and rental business, such as (1) setting prices that farmers can afford, (2) appropriate maintenance, and (3) securing spare parts in case of breakdowns.

Mr Kisho Miyamoto, JICA Rice Extension Specialist, says, “Farm machines with simple functions that are popular in Southeast Asian countries like Thailand and Indonesia are more suitable for Africa. There is room to verify whether high-performance products for the Japanese market are better suited for the dissemination of agricultural machinery to small farmers in Nigeria or whether simpler, less expensive agricultural machinery with simplified performance used in Southeast Asia is more suitable for Nigeria.”

Another issue is whether the market is large enough to be a viable business in terms of securing spare parts in case of breakdowns. The key to building such an ecosystem is to first distribute a large number of agricultural machinery in the market. As the number of used agricultural machinery in circulation increases, more distributors would come up offering genuine spare parts, thereby growing the market. However, another challenge could follow with the distribution of non-genuine spare parts in the market.

Credit Scoring

Many small-scale farmers in Nigeria have low credit ratings and have difficulty utilizing bank loans and guarantees for business transactions. Most deals on the spot are in cash, making it difficult for the farmers to secure large sums of money to expand their businesses. Banks and other financial institutions are often reluctant to provide loans to small farmers, owing to the cost of access to remote and distant areas. 

On the other hand, in addition to access to data on crop sales, purchases, and farm machinery rentals, Zowasel has extensive information on farmers’ personalities, family relationships, and farmland through its efforts to provide farmers with guidance on production methods. This data could be effectively utilized as credit data, especially since MC Nigeria and Zowasel are engaged in the farm equipment rental business

To add more meaning to the data, JICA and Office for Nigerian Digital Innovation (ONDI) launched the “Project for Improving Access to Finance and Livelihoods of Small-scale Farmers” in July 2022 in collaboration with Mitsubishi Corporation Nigeria and Zowasel. The project is an initiative to bridge the gap between financial institutions and small-scale farmers to solve the problems of both parties. This is part of JICA’s “Project NINJA (Next Innovation with Japan)” initiative to promote collaboration between local startups and Japanese companies.

The project’s objective is directly to improve smallholder farmers’ access to finance, expand their businesses, and improve their livelihoods, and in the process, various issues faced by small-scale farmers are expected to be resolved.
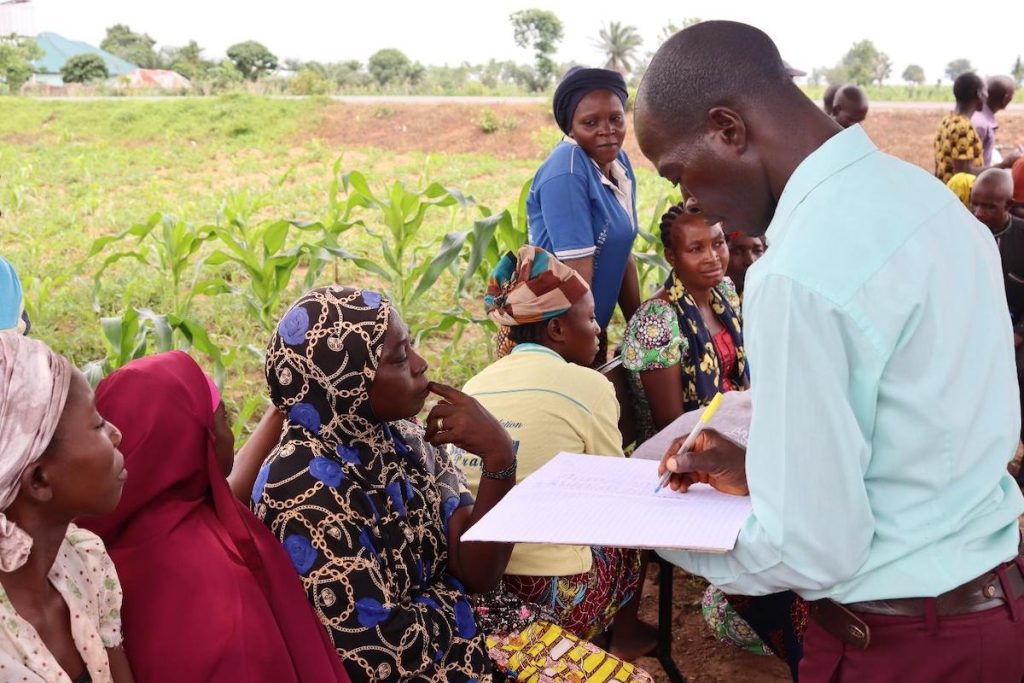
Small farmers in Nasarawa State (left) and Zowacel staff (right) collecting information on farmers

For example, improved access to finance will allow them to use rented farm equipment more, and increased productivity will free up more of their free time, allowing them to start a side business in their spare time. Children who used to help with farming would be able to focus on their schoolwork. In addition, if the improved livelihoods allow for the purchase of a small private power generation system (solar home system, SHS), children can study even in the middle of the night when there is no natural light. For an individual farmer, not only the access to finance will improve, but many other social issues are expected to be solved through derivative effects. 

Furthermore, when the income of small-scale farmers improves, Zowasel, which has close relationships with farmers, will be able to provide a wider range of products and services.

Traceability

The European Union (EU) is debating a new bill aimed at preventing deforestation and forest degradation. Under the bill, 14 commodities to be exported to the EU, including cocoa, coffee, soybeans, beef, and corn, will have to prove that they are not produced on land that has caused deforestation. Since Africa exports many agricultural products to the EU, and cocoa is one of Nigeria’s main exports to Germany, the Netherlands, Spain, Belgium, and other countries, there is concern about the impact of the bill.

Products that meet EU standards will be exported, while those that do not meet standards will be bought cheaply by other countries, potentially putting small farmers in developing countries at a disadvantage. 

In anticipation of the proposed legislation, Zowasel is focusing on traceability to provide data on “where, when, by whom, and how the products it purchases were produced. The company is working with Barry Callebaut AG, a major Swiss company that deals mainly in cacao beans and chocolate products, to promote sustainable cocoa production in Nigeria.

Specifically, agricultural and sustainability experts will be dispatched to production sites to provide guidance to farmers on production, collection of farmland and crop data, as well as gender considerations, forest and environmental protection, and other issues. Barry Callebaut has also pledged to strengthen its support for cocoa cultivation to achieve carbon neutrality by 2025.

Jerry, CEO of Zowasel, said, “The EU bill could be detrimental to small farmers and companies that produce commodities that do not meet EU standards. We want to develop our business in a way that benefits both Nigerian farmers and the EU,” he said.

Strong relationship with farmers

Zowasel’s greatest strength is the direct and strong relationships with farmers that Jerry, CEO of the company, has built and the business he develops by leveraging these strong relationships.

Jerry’s relationship-building is solid and reliable. He spends many days in rural areas during the year, building strong relationships with government officials and town and village mayors in each state. He is very active in explaining the company’s business activities to farmers in the region, and after gaining the approval of smallholder farmers, he onboards them onto the company’s platform.

Zowasel has established 45 crop centres in Nigeria. These centres not only work as service centres of the company but also as a place for farmers to enjoy conversations and build relationships. I visited Ondo State, Nigeria, a cocoa-producing region, in May this year and Nasarawa State in November and was able to experience firsthand the close relationship between the company and the village heads and farmers in these areas.
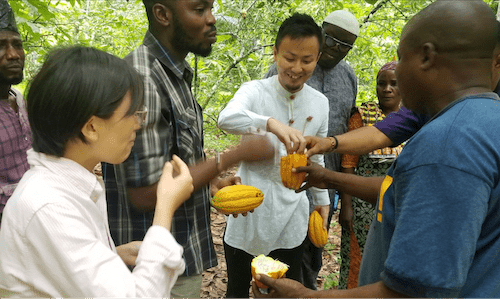
(Cacao farmers in Ondo State with JICA staff)

The business model of Zowasel is time-consuming and human-centric, and the speed of business expansion is slower than that of software startups such as FinTech. However, the company’s strength lies in its “access to small farmers,” a solid network of small farmers that Jerry has built through his visits.

Such a tight-knit network is highly attractive to foreign companies that want to do business with small farmers in Nigeria but do not have a network. Some European companies, such as MAS Seeds of France, are already using the company’s network to conduct demonstrations to adapt their fertilizers, seeds, and other inputs to the Nigerian environment.

How it looks like going forward

Agritech startups targeting small-scale farmers in Africa are increasingly offering one-stop services from production to sales. These services range from agricultural technology guidance, provision of necessary materials at low cost, farm equipment rental services, trading at appropriate prices on online platforms, AI-based credit scoring businesses, and mobile money utilization and financial access services.

Depending on the business model, future agritech businesses targeting smallholder farmers are likely to approach the role of a platform that sells a wide range of offerings, including daily necessities. The business can be more robust by building strong relationships with small-scale farmers and collaborating with more companies to create a value chain.

In business for the BOP (low-income earners/small-scale farmers), collaboration among other industries centred on companies with sales access to customers will be key.

Mr Susumu Yuzurio, Chief Representative of JICA’s Nigeria Office, commented, “While JICA’s business mainly involves government agencies as counterparts, startups have the advantage of building close relationships with end-users. As with the credit scoring project, we would like to actively seek linkages between the startups’ strengths and existing JICA projects in areas such as agriculture and health in order to implement projects with greater impact and solve social issues,” he said.
OPay’s Scrapped IPO Exposes Gap Between African Fintech Hype & Public Market Reality

By Staff Reporter  |  October 31, 2026

The most anticipated African fintech listing in years ended this week not with a bell, but with a quiet thud. SoftBank-backed OPay withdrew its USD 304 M U.S. initial public offering on Friday after a regulatory inquiry in an unidentified foreign jurisdiction spooked the deal hours after it had priced.

The company, which runs one of Nigeria’s largest digital payments platforms, had sold 16 million American depositary shares at USD 19.00 each, the bottom of its marketed range, valuing it at roughly USD 4 B.

The withdrawal is the most concrete signal yet that the wave of multibillion-dollar valuations assigned to African fintechs in private markets does not always survive contact with public investors. OPay is not a failing startup. It swung from a USD 50.8 M loss in 2024 to a USD 72.5 M profit in 2025, and in the first half of 2026 revenue more than doubled to USD 467.1 M while net income nearly quadrupled to USD 90.9 M. But those numbers, impressive in isolation, carry risks that a private valuation can ignore and a public listing cannot.

The first is the source of the profit. OPay markets itself as a payments company. In reality, just over half of its first-half revenue, about USD 236 M, came from loan financing tied to a Nigerian lending book that originated USD 927.6 M of new loans in six months. It charges annualised interest of 18.3% on 30-day loans and 16.8% on 60-day loans, rates that look attractive against Nigeria’s high inflation but depend on a consumer credit cycle that has not been tested through a full downturn. OPay writes off loans after 120 days, far faster than Nigerian banks’ 360-day standard, a sign of how quickly it needs to recycle capital to sustain growth.

The second is currency. OPay earns almost all of its revenue in naira, which has been repeatedly devalued, and reports in dollars. A weaker naira can erase a U.S. investor’s return even while the local business grows. Nigeria accounted for 89.5% of first-half revenue, leaving the company exposed to a single market’s monetary and regulatory trajectory.

The third is the regulatory fog that ultimately stopped the listing. OPay said the inquiry relates to a jurisdiction it considers “immaterial” to its core operations, Reuters reported, but it did not name the regulator or describe the nature of the investigation. That silence is curious.

OPay operates in Nigeria, Indonesia, Egypt and Pakistan, and its founder, Chinese billionaire Yahui Zhou, has business interests across multiple jurisdictions. Investors were asked to accept an undisclosed regulatory risk in a company valued at USD 4 B. When the inquiry surfaced, the underwriters, including Citigroup, Deutsche Bank, Standard Bank and CICC, agreed with OPay to terminate the underwriting agreement rather than proceed.

The collapse also strands a parallel arrangement with Africa’s largest bank. Stanbic Africa Holdings, a Standard Bank subsidiary, had agreed to buy up to USD 200 M in OPay shares through a private placement contingent on the IPO closing, capped at a 4.99% post-listing stake. That investment is now in limbo, along with a proposed secondary listing on the Nigerian Exchange that was meant to give local investors access to a business that derives nearly nine-tenths of its revenue from Nigeria.

OPay’s withdrawal signals the mismatch between the private valuation of African fintechs and the disclosure, governance and currency risks that public investors price. Airtel Money managed to list in London earlier this month at a USD 7 B valuation, but it did so as a subsidiary of a FTSE 100 company with a long regulatory track record. OPay has no such cover. Until it, and the investors who valued it at $4 billion, can name the jurisdiction that stopped the deal, the valuation remains a number on a prospectus.

OPay’s Lending Business Has Quietly Overtaken Its Payments Empire As IPO Nears

By Henry Nzekwe  |  October 13, 2026

OPay has established its place as Nigeria’s ubiquitous payments app for a good few years now. Its green logo is plastered on the walls of roadside kiosks and the phone screens of millions, with the simple pitch of moving money faster than a bank. But the company’s newly filed IPO prospectus reveals a more consequential transformation. Lending, not payments, is now the engine driving its revenue.

In 2024, transaction-based services accounted for 39% of revenue while lending contributed 35%. By the first half of 2026, that hierarchy had flipped. Loan financing alone generated USD 236.1 M, or 50.6% of total revenue, according to the F-1 filing. Payments revenue fell to 28%. The company originated USD 927.6 M in new loans in Nigeria during the first six months of 2026, roughly three times the amount from a year earlier.

The scale of OPay’s lending machine is such that it now has 6.7 million unique quarterly borrowers, more than seven times the number it had in early 2024. Its non-performing loan ratio stood at 4.3% as of June 30, 2026, down from 4.8% a year earlier.

That improvement is down to the company quietly shifting its credit mix away from riskier consumer loans toward merchant lending. In the first half of 2026, the fintech unicorn disbursed USD 99.0 M in merchant loans across 20,000 transactions, generating USD 8.8 M in revenue. The company said it “tightened risk appetite in consumer loans” and shifted toward merchant loans, which carry a lower risk profile, according to the filing.

Consumer lending in Nigeria is politically sensitive and operationally fragile. Borrowers are often informally employed, repayment discipline is uneven, and regulators are watching. Merchant lending is different. OPay can observe a business’s daily transaction flows through its POS terminals and wallet accounts, giving it real-time visibility into cash flow and a natural collection mechanism.

OPay is also quietly rolling out a buy-now-pay-later product. Its BNPL offering allows active users to access short-term credit for everyday purchases with a two-week billing cycle and a one-week repayment window. For now, the product is small. In the first half of 2026, BNPL transaction volume was just USD 5.0 M across 13.4 million transactions. But the company is clearly testing whether the same infrastructure that powers its lending business can support a consumer credit product that feels more like a payment than a loan.

The timing of this lending pivot is not coincidental. OPay filed for a New York Stock Exchange listing under the ticker OPAY, seeking a valuation that reports suggest could reach USD 4 B. Standard Bank Group’s subsidiary has agreed to invest up to USD 200 M through a concurrent private placement, a signal that institutional capital sees value in OPay’s lending economics.

But the filing also exposes the tension at the heart of the model. OPay’s provision for expected credit losses surged to USD 118.4 M in the first half of 2026 from USD 38.1 M a year earlier. The company is lending more, and it is setting aside more to cover the risk of default. Whether merchant lending genuinely lowers that risk or simply delays it remains the central question for investors. One of its main rivals did run into problems with a startup it had lent a sizeable sum to, for instance.

OPay is betting that the same data advantage that made it a payments giant can make it a lending giant too. The prospectus suggests that bet is already paying off. The risk is that in emerging markets, credit cycles can turn faster than payment networks can adapt.

Tech Giants’ Retreat From Africa Continues As Microsoft Guts Kenyan Engineering Hub

By Staff Reporter  |  October 13, 2026

Microsoft has told staff at its Africa Development Centre in Nairobi that the engineering hub will close, ending a seven-year, USD 100 M bet on building global products from Africa and putting nearly 400 jobs at risk.

The decision, communicated to employees on Monday, marks the second retreat from a dedicated engineering presence on the continent after Microsoft shut its Lagos ADC in 2024. Coming just months after a USD 1 B data centre project with Abu Dhabi’s G42 stalled over payment guarantees, the closure signals a broader recalibration of how US tech giants engage with Africa.

The pattern extends beyond Microsoft. X, formerly Twitter, briefly opened an office in Accra, Ghana, in November 2022, then laid off nearly all of its roughly 20 employees just four days later. Former staff said they were “ghosted” without severance pay for more than seven months, and the company reached a settlement only after about a year of negotiations. Kenya has since given X three months to open a physical office in Nairobi, a demand that remains unmet.

Oracle has taken a different path. The company has not closed its Nairobi office but has cut roughly 21,000 jobs globally, about 13% of its workforce, as it redirects capital toward AI and cloud infrastructure. Oracle’s Nairobi operation, which serves as a hub for East African cloud and AI sales, has not been immune.

The company has not disclosed how many Kenyan staff were affected, but termination emails sent in September 2026 gave employees same-day notice, with severance capped at 26 weeks of base salary. Oracle has simultaneously been advertising roles in Kenya for data centre technicians and AI infrastructure sales, a signal that the cuts are a reallocation rather than a full retreat.

Ride-hailing giant Uber has also pulled back sharply from Africa. The ride-hailing giant shut down operations in Nigeria and Uganda in September, capping a year in which it exited four African markets in roughly twelve months, having earlier withdrawn from Tanzania in January 2026 and Côte d’Ivoire in September 2025. Meanwhile, Meta’s termination of a content moderation contract triggered 1,108 job cuts at Sama’s Nairobi hub in April.

The combined effect is a continent increasingly treated as a market for consumption rather than a site for production. The depth of Western involvement raises questions about whose priorities shape Africa’s digital future.

***

Microsoft’s cash spending on property and equipment, mostly data centres, rose from USD 23.9 B in FY2022 to USD 115.9 B in FY2026. Its workforce, meanwhile, fell by 5,000 to 223,000. Capital is flowing into compute infrastructure, not engineering headcount. The Nairobi ADC, whose teams built global products rather than Africa-specific ones, was exposed. Its work could be done from Redmond or Hyderabad. Median entry-level pay for a Microsoft engineer in Kenya stood at roughly USD 52 K a year, against USD 30 K in Bengaluru.

Kenya’s ICT Cabinet Secretary William Kabogo met a Microsoft delegation on Monday and said he “stressed the importance of retaining local talent, protecting jobs at Microsoft’s Nairobi engineering centre and sustaining investor confidence.” The government and Microsoft agreed to develop a joint action plan covering AI adoption, digital government services and cybersecurity.

For Kenya, the closure undercuts a decade-long effort to position itself as a regional technology hub. It follows the stalled Olkaria data centre, which was to be anchored by a geothermal-powered facility and mentored by ADC engineers. Talks broke down in May over Kenya’s reluctance to commit to fixed annual capacity payments.

Africa accounts for 18% of the world’s population but holds less than 1% of global data centre capacity. The continent’s four largest tech economies have each drafted AI strategies acknowledging dependence on US infrastructure as a security concern.

The Nairobi ADC was launched in May 2019 with a pledge of 500 engineers by 2023. By December 2022 it reported more than 500 engineers in Nairobi. Employees were asked to meet with managers by Friday to discuss exit options, including severance terms. Microsoft has not disclosed the timeline for the wind-down or whether Microsoft Research Africa and the Microsoft Garage, both housed at the ADC’s Dunhill Towers office, are included.

The Unlikely Fintech Breakthrough Of Africa’s Biggest Clothing Retailer Rocked By Dispute

By Staff Reporter  |  October 12, 2026

The unlikely thriving fintech arm of Africa’s biggest clothing retailer has investors clashing in a dispute over governance that threatens to overshadow a strategic pivot into financial services.

Pepkor Holdings, the owner of the Pep and Ackermans discount chains, has built a fintech business that is growing far faster than its core retail operations. Revenue from the fintech segment jumped 25.4% to ZAR 4.8 B (~USD 290 M) in the quarter to December, while financial services revenue surged 47.6% to ZAR 2.4 B (USD 144 M). For a company known for selling affordable clothing to millions of low-income shoppers, the numbers are striking. Credit sales now account for 18% of total group sales, up from 16% a year earlier.

That growth explains why Pepkor in July agreed to combine its Flash subsidiary, a payments platform serving 170,000 informal traders, with rival Shop2Shop, which has more than 210,000 users. The deal creates a fintech company valued at about ZAR 21 B (USD 1.3 B), with Pepkor holding a 57.1% stake. Pepkor says the combination will expand its payments, lending and merchant-commerce operations and broaden distribution for a planned digital bank it aims to launch in April 2027.

But the transaction has exposed a governance rift. Some directors voted against the deal, and a top 30 investor, Aeon Investment Management, says shareholders should have voted on a transaction where Pepkor Chief Executive Officer Pieter Erasmus also has a financial interest. Erasmus held a minority position in Shop2Shop before the deal and will own a 13.2% stake in the combined entity, valued at about ZAR 2.8 B (USD 169 M) based on the transaction’s implied valuation.

The transaction does not require shareholder approval under Johannesburg Stock Exchange rules because it falls below the threshold for a related-party transaction. Erasmus recused himself from board deliberations, according to Pepkor.

Even so, seeking shareholders’ views would have demonstrated better corporate governance, according to Asief Mohammed, chief executive officer of Aeon, which holds a 0.4% stake in Pepkor. “It would have gone down better had they done it,” Mohammed said. “Seeking shareholder approval would have been good governance”.

Pepkor says it obtained independent valuations of both businesses and a voluntary independent fair-and-reasonable opinion. The retailer declined to disclose how many directors voted in favour of the deal, citing the confidentiality of board proceedings.

The dispute comes as Pepkor’s shares have dropped 31% this year, compared with a 25% decline on the eight-member FTSE/JSE Retailers Index. The governance concerns also arrive as the company pushes deeper into financial services to find growth beyond its core discount retail operations, a strategy that has delivered tangible results but now faces heightened scrutiny over board process and shareholder rights.

The planned listing of the combined fintech business, provisionally called FintechCo, in the medium term adds another layer of complexity. Pepkor is betting that its informal market platform and merchant network can become a standalone fintech powerhouse. Whether investors will reward that bet depends partly on how the company manages the governance questions the deal has raised.

Beyond A Button: SeerBit Takes On The Real Gap In African Cross-Border Payments

By Henry Nzekwe  |  October 12, 2026

In Accra, a beauty brand built its following on TikTok and Instagram, reaching customers in the UK who liked the products enough to buy. The merchant had done the hard part, creating something people wanted and finding them online. But when a British customer reached checkout on the brand’s website, the payment experience was unfamiliar, and the sale slipped away.

That scenario, described by Omoniyi Kolade, founder and CEO of the pan-African payments company SeerBit, captures the shift now underway in African digital commerce.

In August 2026, SeerBit announced it had integrated PayPal into its checkout infrastructure, allowing merchants across its 10 African markets to accept payments from PayPal’s more than 400 million users. The integration runs alongside the local payment methods SeerBit already supports, including cards, bank transfers, and mobile money, and gives merchants a single dashboard to manage local and international transactions.

The announcement was framed as a milestone for African businesses seeking global customers. But the more revealing story lies beneath the press release, in what the partnership exposes about PayPal’s complicated history on the continent, the limits of a single integration and where the real bottlenecks in African cross-border commerce have shifted.

PayPal’s relationship with Africa is marked by two decades of exclusion. In 2004, the company restricted inbound payments to Nigeria, citing fraud and chargeback risks, a policy that locked out a generation of freelancers and online businesses. A 2014 partnership with First Bank allowed outbound payments only, and a 2021 Flutterwave link served businesses while ignoring individual users. Those restrictions remained in place for 22 years.

During that absence, Nigerian fintechs including Paga, Flutterwave and Paystack built the infrastructure PayPal had declined to provide, capturing a domestic digital payments market that reached NGN 1.07 Q (USD 702.6 B) in 2024.

***

Kolade is careful not to frame the SeerBit integration as a correction of that history. He describes a different set of changes that made the partnership possible now. African businesses became more digitally discoverable, consumers grew more comfortable buying across borders, and local payment infrastructure matured enough for global networks to connect to something reliable.

“The shift isn’t simply that African merchants suddenly want PayPal,” Kolade told WT. “It’s that the commercial relationship between an African business and a customer somewhere else in the world is becoming much more normal.”

What that relationship requires, however, is not simply a payment button, the founder emphasised. When SeerBit integrated PayPal, the company had to build additional merchant verification layers, because PayPal was extending its network to businesses it did not know directly.

It also created dedicated support and escalation processes, cutting resolution times for merchant issues from as long as 90 days to 24 hours. And it had to account for the fact that Africa is not a single payments market. Regulatory environments, banking infrastructure and settlement realities differ across every country SeerBit operates in. The complexity is not the integration itself, Kolade said, but everything around it.

Even after those layers are addressed, the merchant’s work is not finished when a payment notification arrives. Kolade argues that accepting payment is becoming less of a bottleneck, and that the harder problem now is what happens after the customer has paid.

A cross-border transaction must still be settled, often across multiple currencies and institutions. The merchant has to understand what they have actually earned after fees and foreign exchange costs, reconcile it against orders, and then access those funds where the business needs them. “For me, the next frontier is less about, can I accept this payment, and more about, can I make the money useful,” Kolade said.

That post-payment journey is where fragmentation becomes expensive. If a business sells into several markets and collects through different currencies, methods and providers, the money can pass through several institutions before it becomes usable. That ties up working capital, creates reconciliation work and makes it harder to understand true margins. It is a problem that a checkout integration does not solve, he reiterated.

***

There is also a quieter dynamic at play. Kolade points out that the merchant does not have to be an exporter for cross-border payments to matter.

“Someone in Canada might want to order food for their parents in Nigeria. Someone in the diaspora might pay for groceries or a pharmacy purchase for a family member back home. An international visitor in Ghana or Kenya might want to use the payment method they already know,” he volunteered as examples.

In these cases, the merchant remains local while the customer is international. And the founder asserts that the boundary between a local business and a global customer is becoming less important, and that changes what merchants expect from their payment infrastructure.

PayPal’s broader strategy, PayPal World, is designed to connect global payment networks with local wallets and infrastructure rather than building the entire stack itself. Kolade sees this as a recognition that the foundational work has already been done by African companies. “This isn’t one company coming in to solve African payments,” he said. “A lot of that foundational work has already been done by African companies.”

Still, the integration raises questions that the announcement does not answer. Cross-border payments in Africa remain expensive, with the World Bank estimating that sending USD 200.00 to Sub-Saharan Africa costs more than 8% on average, compared with a global average of around 6%. Currency volatility and central bank restrictions on hard currency can delay or complicate settlements. Merchants will need to understand how PayPal transactions are priced, how quickly funds settle and how disputes are handled.

For PayPal, the African market is a growth opportunity at a time when its core markets are maturing. For SeerBit, the partnership strengthens its position as a checkout aggregator that handles both local and global payment methods. For African merchants, the integration removes one obstacle at the point of sale. Whether it changes the economics of selling across borders depends on what happens after the customer clicks pay.

Moove Quits Nigeria, Its Birthplace, As Global Ambitions Trump Difficult Home Market

By Staff Reporter  |  October 8, 2026

Moove, the mobility fintech founded in Lagos in 2020, announced on Thursday it will conclude operations in Nigeria, the market that incubated its business model and launched its global trajectory. The company will transfer vehicles worth approximately NGN 35 B (USD 22 M) to eligible Nigerian customers free of charge from October 1, 2026.

The exit comes just over a month after Uber Technologies ended its operations in Nigeria on September 2, a departure that rendered Moove’s core model in the country untenable. Moove built its Nigerian business by financing vehicles for Uber drivers, with repayments tied to daily earnings. When Uber left, that data pipeline collapsed, leaving drivers uncertain and Moove’s local unit without a platform partner to anchor loan recovery.

Moove, now headquartered in Dubai, reached a USD 2.1 B valuation in August after raising USD 250 M in a Series C round led by Abu Dhabi sovereign wealth fund Mubadala. Its annual recurring revenue climbed from roughly USD 275 M in 2024 to about USD 400 M in 2025, before hitting USD 420 M following acquisitions including Brazil’s Kovi and Tokyo Taxi in Japan. The company operates about 42,000 vehicles across 29 cities in 13 countries and employs roughly 3,300 people.

Yet the Nigerian market that produced this global platform became a drag. A currency mismatch defined the problem. Moove raised dollar-denominated debt to buy vehicles while drivers earned naira, a disparity that widened sharply after Nigeria’s 2023 fuel subsidy removal drove up pump prices and compressed driver margins. The company had already weathered a repayment crisis, repossessing vehicles from drivers who could not earn enough to meet obligations.

“While Nigeria remains deeply important to our story, the operating environment has become increasingly challenging,” Moove said in a statement announcing the exit, framing the vehicle transfer as a “thank you” to customers.

The company’s pivot toward autonomous mobility has reshaped its strategic centre of gravity. Through a partnership with Alphabet’s Waymo, Moove manages autonomous vehicle fleets in Phoenix and Miami, with London planned next. It is the largest global fleet partner for Uber and is positioning itself as a neutral infrastructure layer for robotaxi operations, a role that has attracted investment from Toyota’s growth fund Woven Capital.

Co-founder Ladi Delano, now based in Dubai, has spoken of building a business that solves problems his parents’ generation faced in Nigeria, but the company’s current growth is driven by markets far from Lagos.

Moove did not disclose a timeline for completing the wind-down or the number of employees affected. The company said eligible customers would take full ownership of their vehicles with no further payment required for the vehicles themselves from October 1. Remaining obligations, if any, were not specified.

The transfer of NGN 35 B in assets to drivers is an unusual exit gesture, one that may cushion the immediate blow for Moove’s Nigerian customers. But it does not change the broader signal that a company built to democratise vehicle ownership in Africa has concluded that ownership of its own future requires leaving Africa’s largest market behind.

M-KOPA Built Its Name On Solar—Now Smartphones & EVs Drive A USD 600 M Boom

By Henry Nzekwe  |  October 8, 2026

Africa-focused fintech M-KOPA reported a 45% surge in revenue to USD 600 M for its 2025 financial year, a milestone that underscores how the Kenya-based company’s decisive shift from solar financing to smartphone and electric vehicle asset financing has reshaped its business and its balance sheet.

The company, which marked its 15th anniversary this month, said it added three million customers in the past year, bringing its total to 10 million across Kenya, Nigeria, Ghana, Uganda and South Africa.

The growth was driven less by its original solar home systems and more by credit-financed smartphones, a category M-KOPA entered only in 2020. Since that pivot, revenue has compounded at an annual rate of 50%, transforming what was once an impact-driven energy company into one of Africa’s largest consumer-financing platforms.

The shift reflects a hard economic reality across its markets. The vast majority of everyday earners lack formal salaries or credit histories, yet demand for smartphones and income-generating electric vehicles has outstripped the addressable market for financed solar panels.

“We maintained profitability while reinvesting as much as possible in our products, technology and distribution to scale our reach across Africa’s massive, underserved market of everyday earners,” Chief Financial Officer Faraimose Kutadzaushe said in a statement.

That reinvestment is now visible in two areas. First, the company says its Nairobi assembly plant is the largest smartphone factory in Africa by volume, producing over two million devices since its opening in 2023 and employing more than 400 workers.

On the other hand, the company has financed more than 10,000 electric motorcycles and three-wheelers in Kenya, with rider data showing average daily savings of KES 530.00 (USD 4.10) from lower energy and maintenance costs. M-KOPA is now expanding that pay-as-you-go model to electric tuk-tuks, targeting a broader segment of Kenya’s commercial transport sector.

M-KOPA says it onboards approximately 10,000 new customers per day and processes micropayments at a rate of 23 times per second, showing operational heft underpinning its expansion. It employs over 2,500 full-time staff and supports nearly 50,000 sales agents, making it one of the largest private distribution networks in African consumer finance.

Yet the USD 600 M revenue figure masks a strategic vulnerability that management has moved to address. M-KOPA’s entire financing model depends on its ability to remotely lock financed smartphones when customers fall behind on repayments.

In March 2026, the company acquired Finnish software firm KilpiTek for approximately USD 8 M, bringing that device-locking capability in-house rather than relying on a third-party provider. The transaction included about USD 2.67 M in cash and the remainder in M-KOPA shares and deferred consideration, according to its financial disclosures.

“The transaction is intended to strengthen the group’s control over a critical component of its technology stack and support ongoing product and sourcing strategy,” the company said in its disclosure.

The broader question for investors is whether M-KOPA’s smartphone-led model can sustain its growth rate as it expands across five markets with varying regulatory and currency environments. The company has been recognised on the Financial Times Fastest Growing Companies in Africa list for five consecutive years, but its customer base remains heavily concentrated in East Africa, and its newest markets in Nigeria and Ghana present different competitive and macroeconomic challenges.

For now, the numbers point to a company that has found a more durable product axis than the one it was founded on. While solar gave M-KOPA its first decade and its patient-capital base, smartphones and electric mobility appear to be giving it its next one.

Africa’s Traditional Savings Groups Quietly Emerge As New Payments Battleground

By Henry Nzekwe  |  October 7, 2026

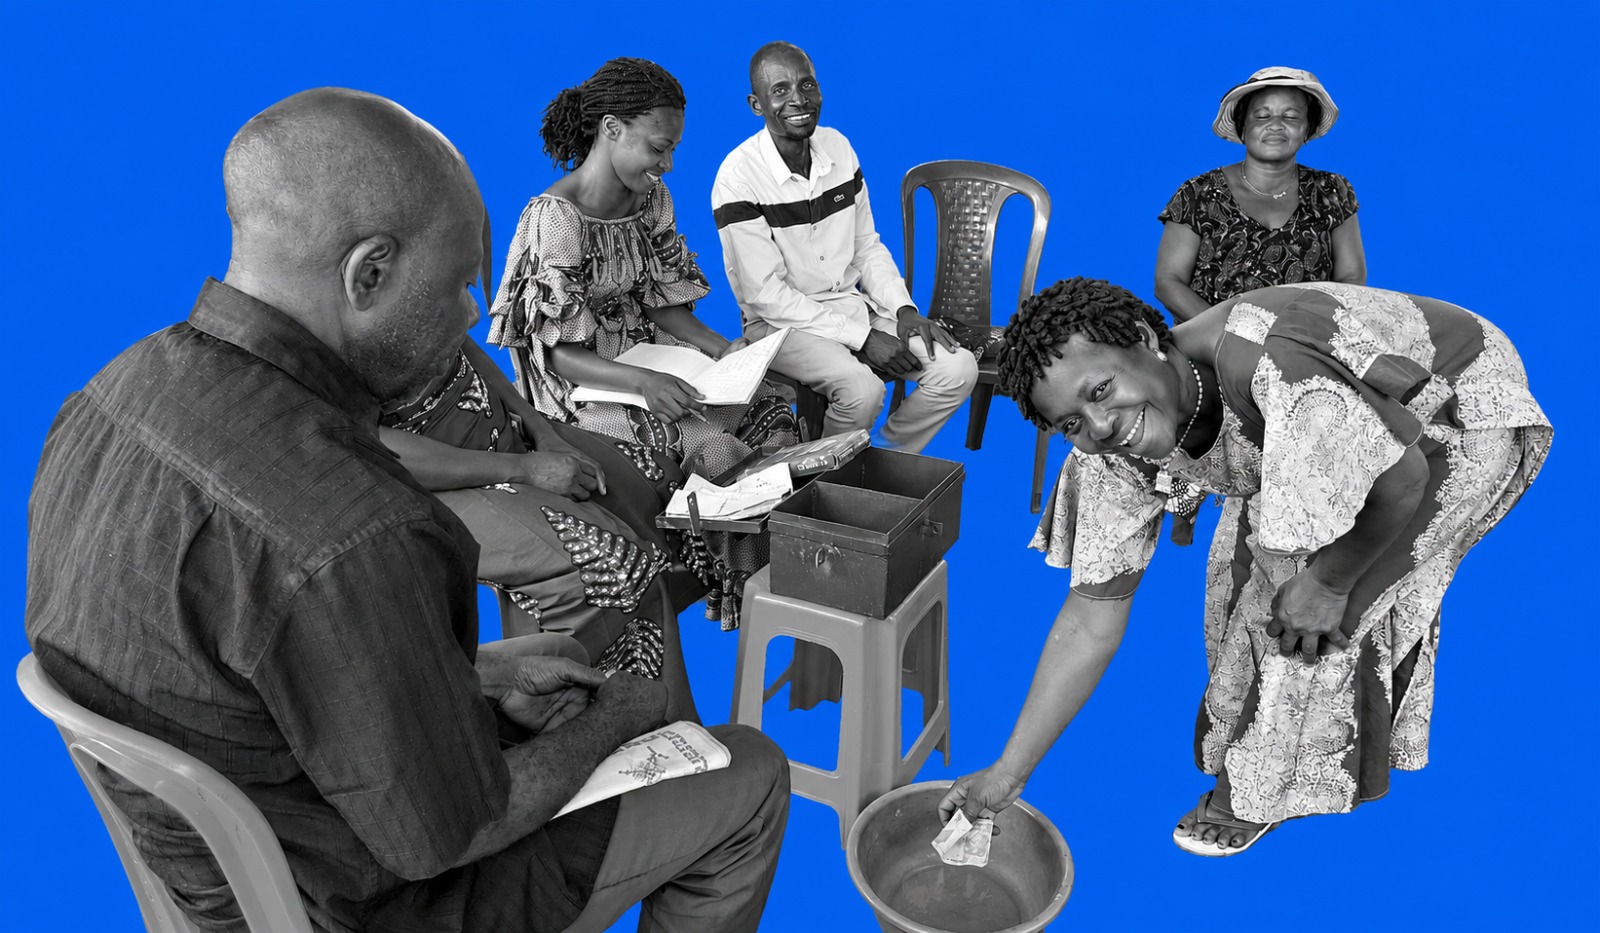
Across Africa, an old financial habit is becoming a new frontier for banks, fintechs, and mobile money providers. Community savings groups, long dismissed as the informal domain of cash-stuffed envelopes and handwritten ledgers, are being pulled into the digital economy at speed. The prize is not just the deposits they hold, but the transaction flows they generate.

The numbers explain the sudden interest. Kenya’s regulated savings and credit cooperative organisations held KES 1.21 T (USD 9.4 B) in assets in 2025, up 12.5% from a year earlier, according to the Sacco Societies Regulatory Authority. South Africa’s 800,000 stokvels manage about ZAR 50 B (USD 2.7 B) annually and count roughly 11 million members. Egypt’s MoneyFellows, which digitises the traditional gameya savings circle, says it has onboarded more than 8 million users.

These pools of money once sat largely outside the banking system. Now they are becoming the connective tissue for a payments market that banks cannot afford to ignore.

The competitive dynamic is most visible in Kenya. Commercial banks are racing to handle cheque clearing, ATM access, and real-time transfers for deposit-taking SACCOs, which are barred from direct access to the national payment infrastructure. Co-operative Bank of Kenya served 110 SACCOs with ATM connectivity in 2025, but Family Bank, KCB, and Equity Bank are expanding their footprints. Safaricom and payment provider Interswitch have entered the Pesalink instant transfer market for SACCOs, a sign that the settlement landscape is widening beyond traditional lenders.

SASRA reported that the number of SACCOs offering digital financial products rose to 267 in 2025 from 236 a year earlier. But the same report warned of cyber risks, and 107 regulated SACCOs still had no USSD connectivity at all. The digitisation race is real, but it is uneven.

***

In South Africa, the battleground is account opening. First National Bank completed the full digitisation of its stokvel accounts in early 2026, removing a long-standing requirement for three signatories to visit a branch together.

“We’ve completed the digital stokvel account journey and now everything, from account opening through to transactions and payouts, can now be done digitally,” said Himal Parbhoo, FNB’s CEO of cash investments. Standard Bank, Nedbank, and Absa offer stokvel accounts, but none have matched FNB’s end-to-end remote onboarding.

The broader significance lies in what happens to the money once it is inside a bank. Stokvel balances are stable and predictable, building through the year before seasonal payouts. For lenders, they are a low-cost source of funding. For members, formal accounts offer security. The trade-off is that community savings are being slowly absorbed into the same institutional structures they were designed to bypass.

Egypt offers a different model. MoneyFellows, which raised USD 13 M in 2025, has built a profitable business by digitising the gameya without requiring users to join pre-formed social circles.

“We’ve managed to crack this model and achieve profitability,” said founder and CEO Ahmed Wadi. “What makes this even more transformative is that we’ve facilitated billions in loans without using working capital.” The platform’s ability to generate credit scores from savings behaviour has turned a cultural tradition into a data asset.

Nigeria is also in the picture as new vigour seeps in after some previous stop-start endeavours. Rank, a fintech formerly known as Moni, launched Money Circles in 2026, a digital version of ajo and esusu rotating savings schemes. The company says it has paid out more than USD 100 M to users in the past year.

“For generations, Africans have relied on communal financial structures to build wealth,” said CEO Femi Iromini. “We are bringing these trusted traditions into the modern age by layering cutting-edge technology.”

The race is not without friction. Digitising savings groups requires trust, and trust is not easily coded. Many groups still prefer cash because it is visible. Others worry that formal accounts will expose them to fees or taxes. Regulators, meanwhile, are caught between encouraging financial inclusion and managing new risks.

What is clear is that the infrastructure behind community savings is becoming a market in its own right. Banks want the deposit base, fintechs want the transaction data, and mobile money providers want the payment rails. The savings groups themselves want convenience and security. Whether those interests align or collide will shape how hundreds of millions of Africans save, borrow, and build wealth in the years ahead.

Feature Image Credits: WVI

Cash-Back At Supermarket Tills Surge As South Africans Ditch ATMs Over Fees

By Staff Reporter  |  October 7, 2026

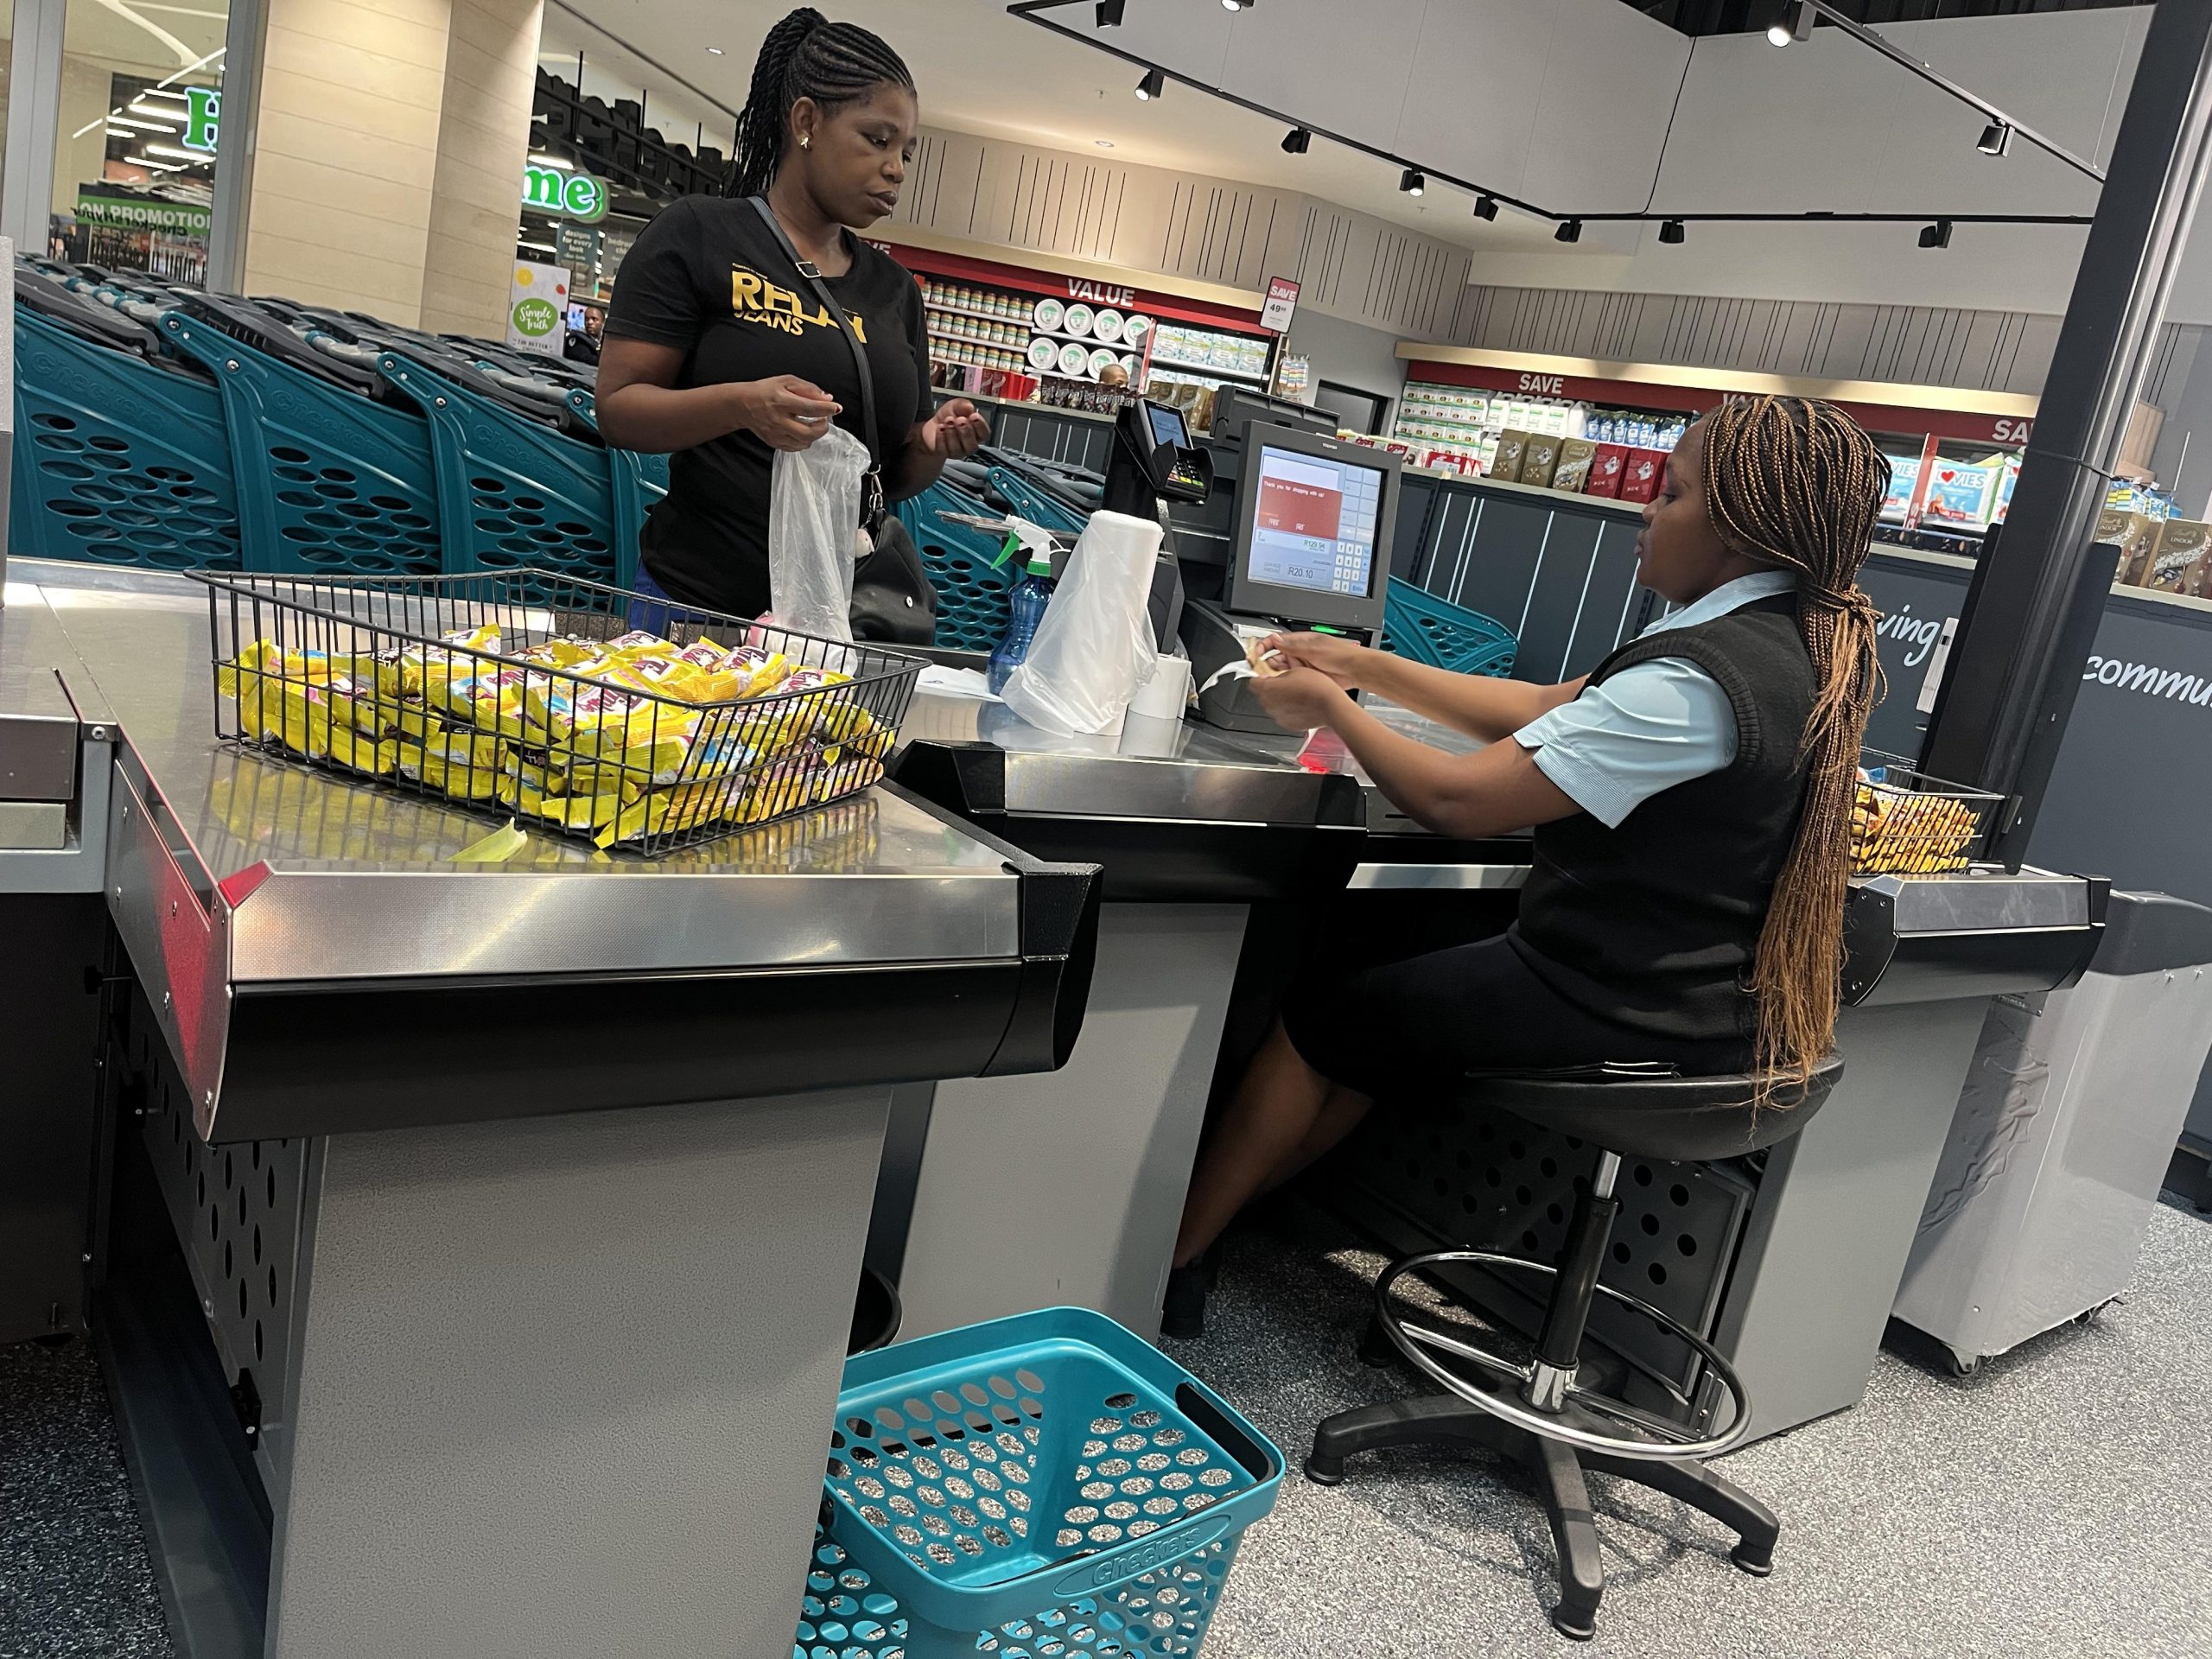
South Africans are abandoning automated teller machines (ATMs) for an unlikely alternative. They are withdrawing cash at supermarket checkouts, and the shift is forcing a rethink of how the country’s cash system works.

Data from the South African Reserve Bank’s Cost of Cash Industry Report 2026 shows retail tills now process about ZAR 326 B (USD 19.5 B) in cash-back withdrawals annually across 663 million transactions, with an average withdrawal of ZAR 492.00 (USD 25.25). The SARB describes point-of-sale cash-back as the most cost-efficient channel in the country, costing about 12 cents per ZAR 100.00 (USD 6.01) handled compared with 68 cents at ATMs and ZAR 1.53 at bank branches.

South Africans pay about ZAR 17.7 B (USD 1.06 B) a year in cash withdrawal fees, with ATM withdrawals typically costing between ZAR 10.00 (USD 0.60) and ZAR 20.00 (USD 1.20), while tillpoint withdrawals range from ZAR 1.00 (USD 0.060) to ZAR 3.00 (USD 0.18). Consumers also spend an estimated ZAR 12.5 B (USD 751.4 M) on taxi fares and fuel to travel to ATMs and bank branches, and lose another ZAR 27.8 B (USD 1.6 B) in productivity from queuing and travel. For many households, the supermarket till is simply closer and cheaper.

The country operates about 30,634 ATMs, but three of the five largest banks have reduced their ATM footprints since 2023. Nedbank’s network has shrunk by 4.4% and Absa’s by 2.3%, while Capitec has expanded aggressively. The average ATM costs about ZAR 307.59 K (USD 18.4 K) a year to operate, a burden that gets passed to consumers.

Banks are actively steering customers toward retail tills. Standard Bank says cash-back at point-of-sale has surged more than 100% since 2019, and 11% of all its cash withdrawals now happen at retail checkouts.

“Emerging channels like cashback at point-of-sale and cash deposits at retailers are gaining traction as alternatives to ATMs and branches,” said Kabelo Makeke, Standard Bank’s head of personal and private banking in South Africa.

Retail tills solve a problem ATMs cannot. ATMs dispense high-value ZAR 100.00 and ZAR 200.00 notes and cannot issue coins, which creates friction for consumers who need smaller denominations for taxi fares and informal traders. SARB field research found shoppers deliberately buy low-cost items with large notes to obtain change in smaller denominations.

The shift has broader implications. Retailers can recycle cash from sales directly to customers, reducing their own banking and cash-in-transit costs. But it also raises questions about whether the retail sector is becoming an unofficial banking infrastructure without the regulatory framework that comes with it.

The SARB’s Cash Smart Strategy, outlined in a position paper earlier this year, proposes white-label ATMs operated by a national cash utility rather than individual banks, with the aim of lowering fees and expanding access to underserved areas. Deputy Governor Rashad Cassim said the central bank is aware that many businesses operate under current regulations and that engagement on the proposals is ongoing.

Nevertheless, the supermarket till remains the most practical option for millions of South Africans.

Viral Simulator Games On Browser Tabs Make A Splash In Nigeria’s Scale-Starved Gaming Scene

By Henry Nzekwe  |  October 6, 2026

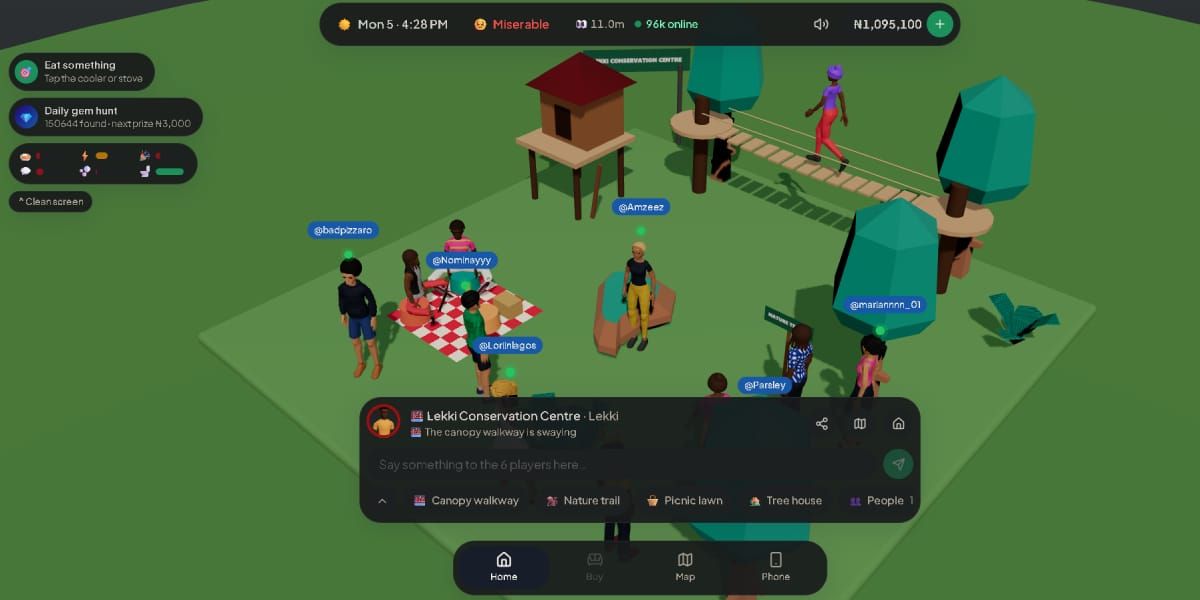
A browser game that lets Nigerians simulate life in Lagos, complete with traffic, power cuts, and the struggle to make rent, has drawn more than 2 million players in under a week, marking a breakout moment for a local gaming industry that has long struggled to turn cultural familiarity into scale.

Lagos Life, built by UK-based Nigerian developer Shalom Mathew, went live on October 1, Nigeria’s Independence Day. Within three days, it had crossed one million players.

By October 5, its public dashboard showed more than 2 million total players, over 145,000 concurrent users and 16.5 million all-time visits, having added two other major cities, Abuja and Port Harcourt, to the virtual world. The game generated USD 46.9 K in revenue in its first four days, according to figures Mathew shared on X, where she posts as @Shalom_HeyEliy.

The game is quite simple. Players create a character and are assigned a starting financial position: either “Nepo,” a reference to wealth and connections, or “Lapo,” a nod to the microfinance loans and financial hustle that define life for many young Nigerians. From there, they work jobs, manage energy, buy food, pay rent, and socialise in a shared online Lagos that includes landmarks like Amala Shitta and Quilox. The game runs in real time, so its virtual day follows the actual day.

Mathew has said the idea grew from her childhood spent playing The Sims 3. “I grew up playing The Sims 3 and always wondered what it would be like if the Sims lived in a world inspired by ours,” she wrote on X.

She credits another Nigerian browser game, Lagos Run, with providing motivation. Lagos Run, built by Berlin-based engineer Opeyemi Adeniran, puts players behind the wheel of a danfo, the yellow minibuses synonymous with Lagos transport. Released in late September, it drew more than 20,000 players within days.

***

What separates Lagos Life from the wave of Nigerian games that have come before it is not the cultural references is the distribution model. The game requires no download, no app store listing and no console. A phone or computer with a browser is enough. That matters in a market where the cost of data, device storage and gaming hardware has historically kept participation low.

About 87% of African gamers play on smartphones, and mobile titles account for nearly 90% of the continent’s gaming revenue, but credit card penetration in Nigeria sits at around 3.5%, making paid downloads and in-app purchases difficult. A free browser game sidesteps all of that as the link is effectively the product.

The speed of adoption reflects how little it takes to reach Nigerian players when the barrier to entry is removed. Google Trends data shows Nigerian search interest in “Lagos life” broke out by more than 5,000% in the week after launch, peaking at about 10 p.m. on October 4.

Interest was strongest in Ekiti, Ogun, Osun and Lagos, but the game’s reach extended well beyond the southwest. Nigeria now has over 46 million active gamers, more than South Africa’s 26 million, and its gaming market is growing at roughly 12% annually, well above the global average.

***

The commercial model is equally notable. Unlike most viral Nigerian games, Lagos Life has been generating revenue from day one, renting out virtual billboards to real advertisers. The game charges NGN 5 K (USD 3.77) per week for one of 38 roadside billboards and NGN 18 K (USD 13.56) for a larger lagoon plot. It also offers artists the chance to have their music played in virtual clubs for NGN 50 K (USD 37.74).

That revenue is important as running a free game with tens of thousands of concurrent users is expensive. Moreover, Lagos Life suffered a brief outage on October 2, for which Mathew compensated every player with NGN 100 K (USD 75.48) in virtual cash, a sum that exists only inside the game.

The explosive growth has also exposed the fragility of a game built quickly and scaled overnight. An exploit allowed some players to generate vast sums of virtual money, flooding the in-game economy with hacked naira. Mathew reset the fraudulent balances, restored legitimate ones and said she was adding features such as income tax to prevent a recurrence. Players mostly joked about the intrusion of real-world financial burdens into their virtual escape.

The game’s success has already spawned imitators. A London Red Bus game appeared within days of Lagos Run, swapping the danfo for a double-decker. A Port Harcourt life simulation followed Lagos Life.

Whether Lagos Life retains its audience beyond the initial curiosity is uncertain. A visit of a few minutes counts toward the total, and viral browser games often lose players once the novelty fades. But the early numbers suggest that the barrier for Nigerian games was access, not demand.

It does seem that when a game is a link, not a download, and when its world looks like the one outside the window, the audience is already there.